Overall Market Commentary
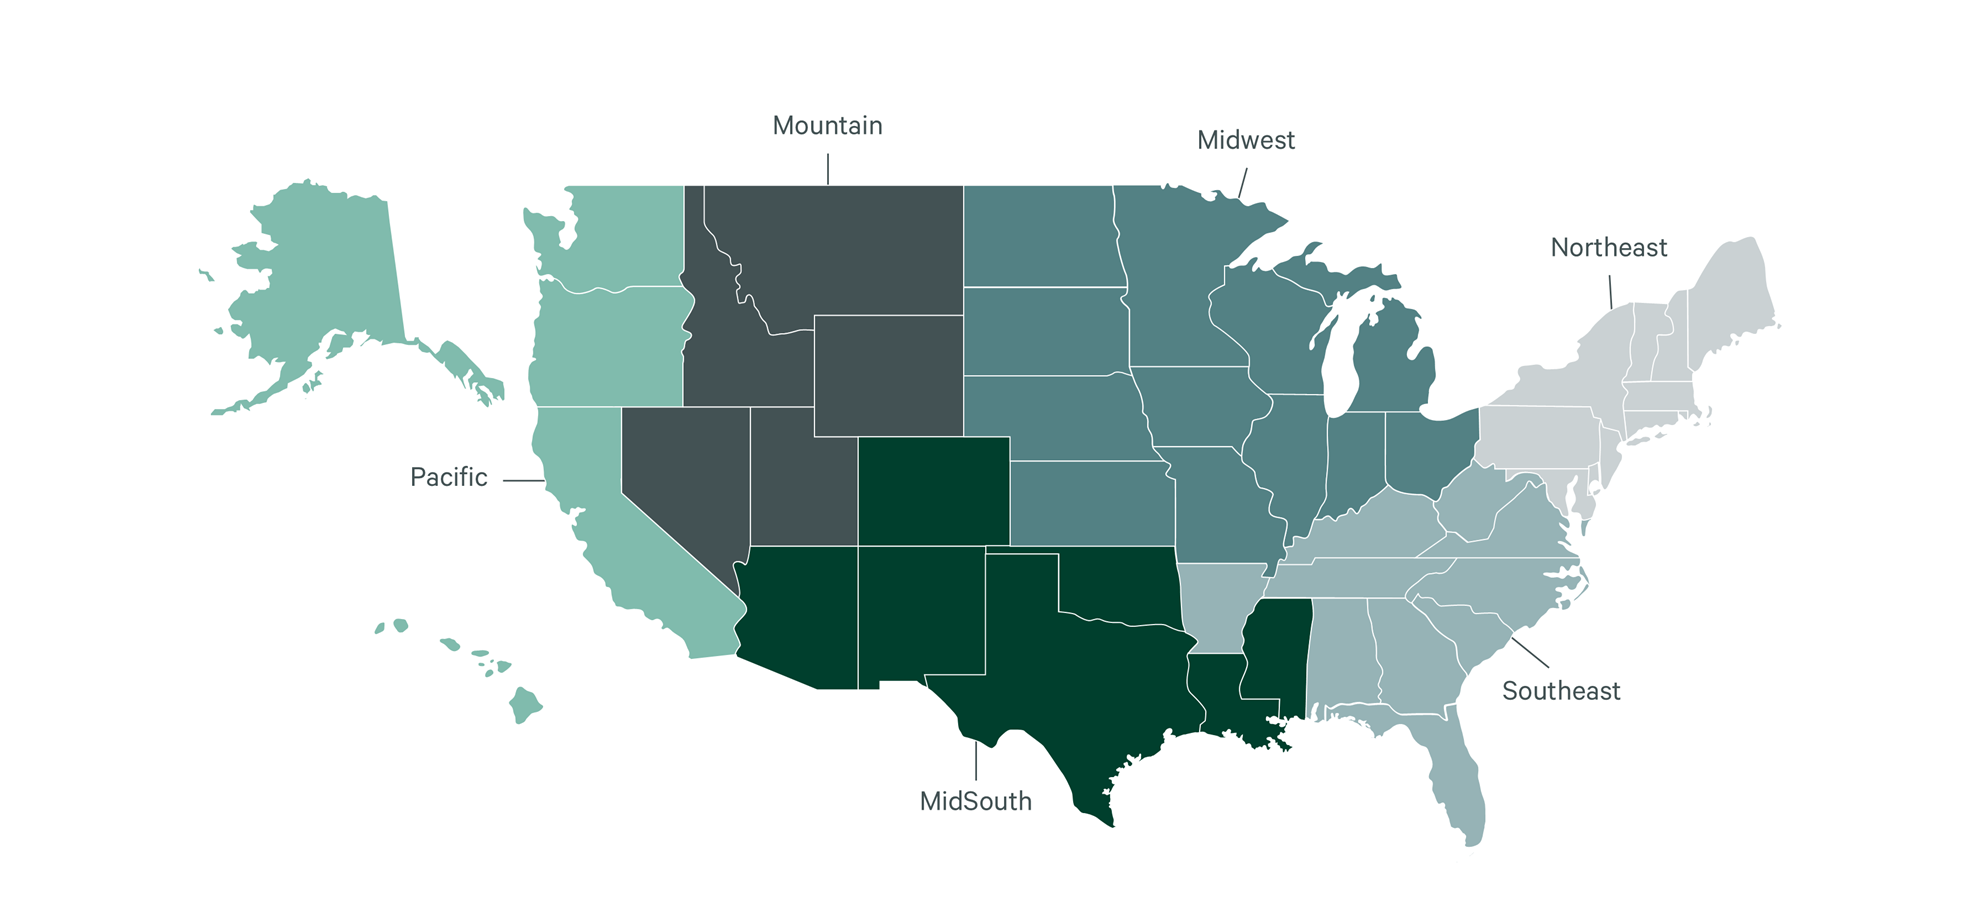
High barriers to entry continue to define the Pacific self-storage market, where restrictive zoning and dense urban development have pushed Class A cap rates down to 4.70%, the lowest in the nation. Even conservative brokers note that cap rates in the region rarely exceed 6.00%.
But in the Mountain region, where inventory is significantly smaller, the risk profile changes. Limited Class A transaction activity has kept cap rates relatively tight, ranging from 5.25% to 6.12%, while Class B and C assets in secondary and tertiary markets have seen cap rates rise above 10.19%. The market is increasingly bifurcated, with motivated sellers offering higher yield premiums to attract cautious investors. Similar dynamics are emerging in the Pacific region, where Class B/C self-storage assets are trading at cap rates above 9.10%.
Across every region, broker sentiment is generally optimistic due to historical performance but is not necessarily reflecting the reality of the transaction data.
The Northeast: Brokers remain optimistic, citing an upper cap-rate range of 6.50%, but recent Class A transactions have reached 6.75%, while lower-tier assets have traded as high as 8.00%, reflecting growing risk differentiation across the market.
The Midwest: Brokers predict a stable 5.50% to 6.50% cap-rate range, yet recent Class A transactions averaged 6.91%, while lower-tier assets traded as high as 8.52%, highlighting a widening gap between core and non-core property pricing.
Overall, year-to-date transaction volume has increased nationally, though activity remains below the peaks reached in 2022. While the Federal Reserve recently implemented a modest rate hike, the move was widely anticipated and largely priced into the market. Class A transaction activity remains subdued, with the greatest potential for increased sales volume concentrated in Class B and C assets across secondary markets.
Self-Storage Market Perspectives by Region
Northeast Self-Storage Capitalization Rate Ranges
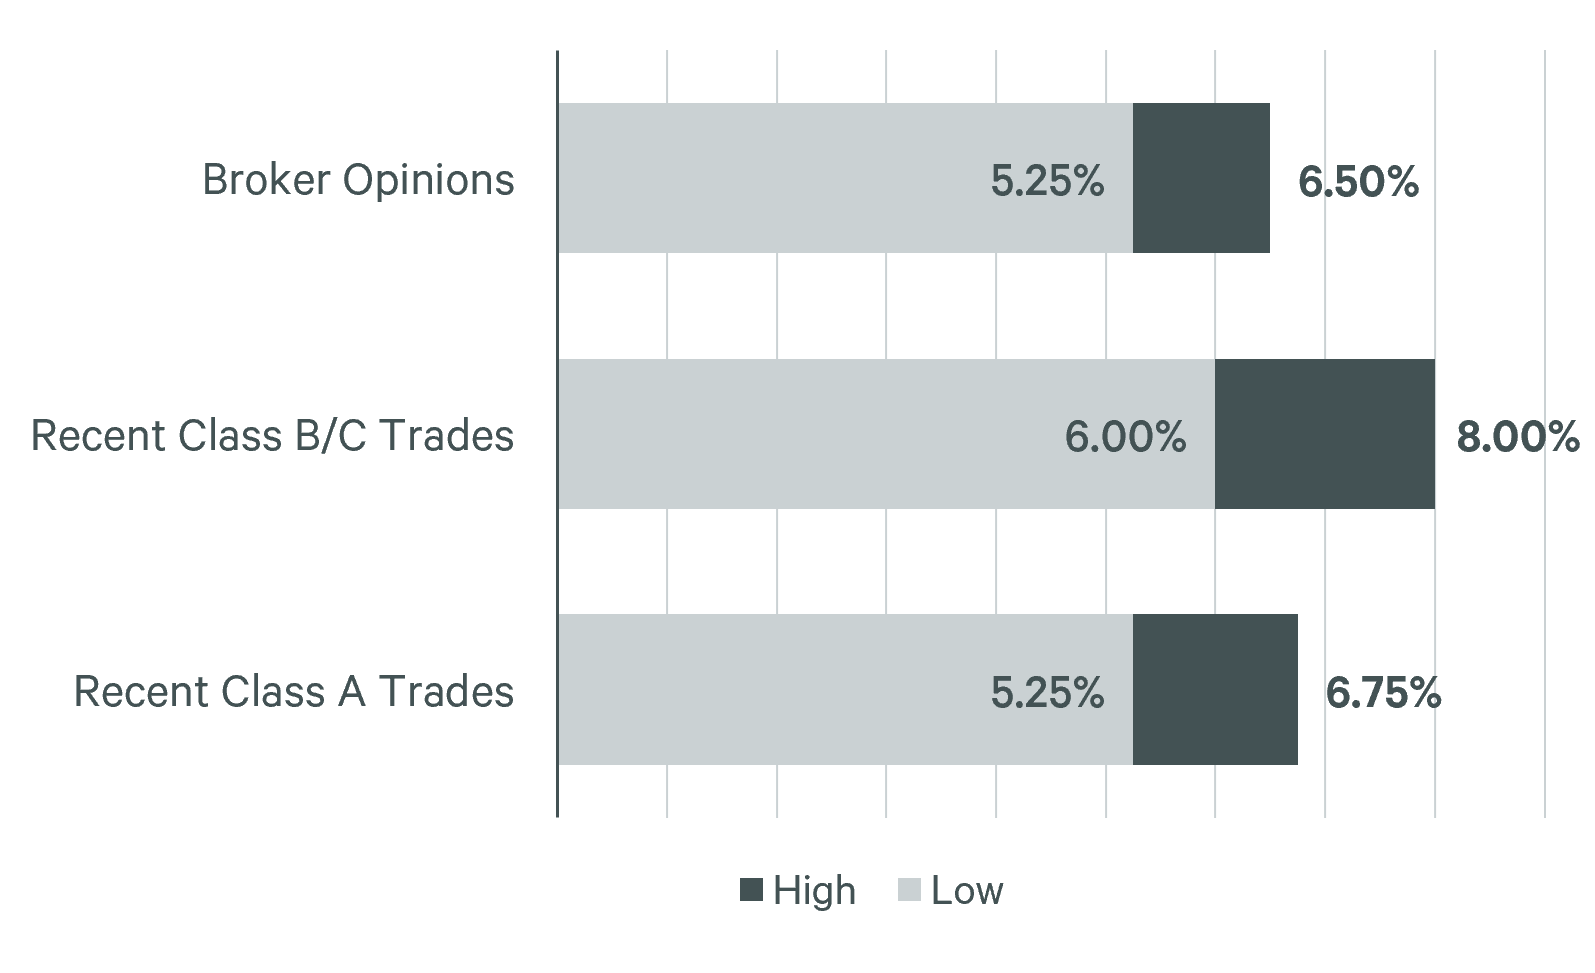
Recent trades of Northeast self-storage properties reflect capitalization rates on average range from 5.25% to 6.75%, while broker market opinions compress that range to 5.25% to 6.50%. Drive-up facilities trade at wider capitalization rates of 6.00% to 8.00%, reflecting the lower barrier to entry and reduced revenue intensity of single-story, non-climate product.
Most of the transaction volume is concentrated within the suburban submarkets located just outside the primary metropolitan areas of New York City, Boston, and Philadelphia.
Notable recent sales include StorQuest Self Storage in Bedford Hills, New York, August 2026 - $23.45m and Extra Space Storage at 319 Tonnelle Ave, Jersey City, NJ - $34.5m.
Southeast Self-Storage Capitalization Rate Ranges
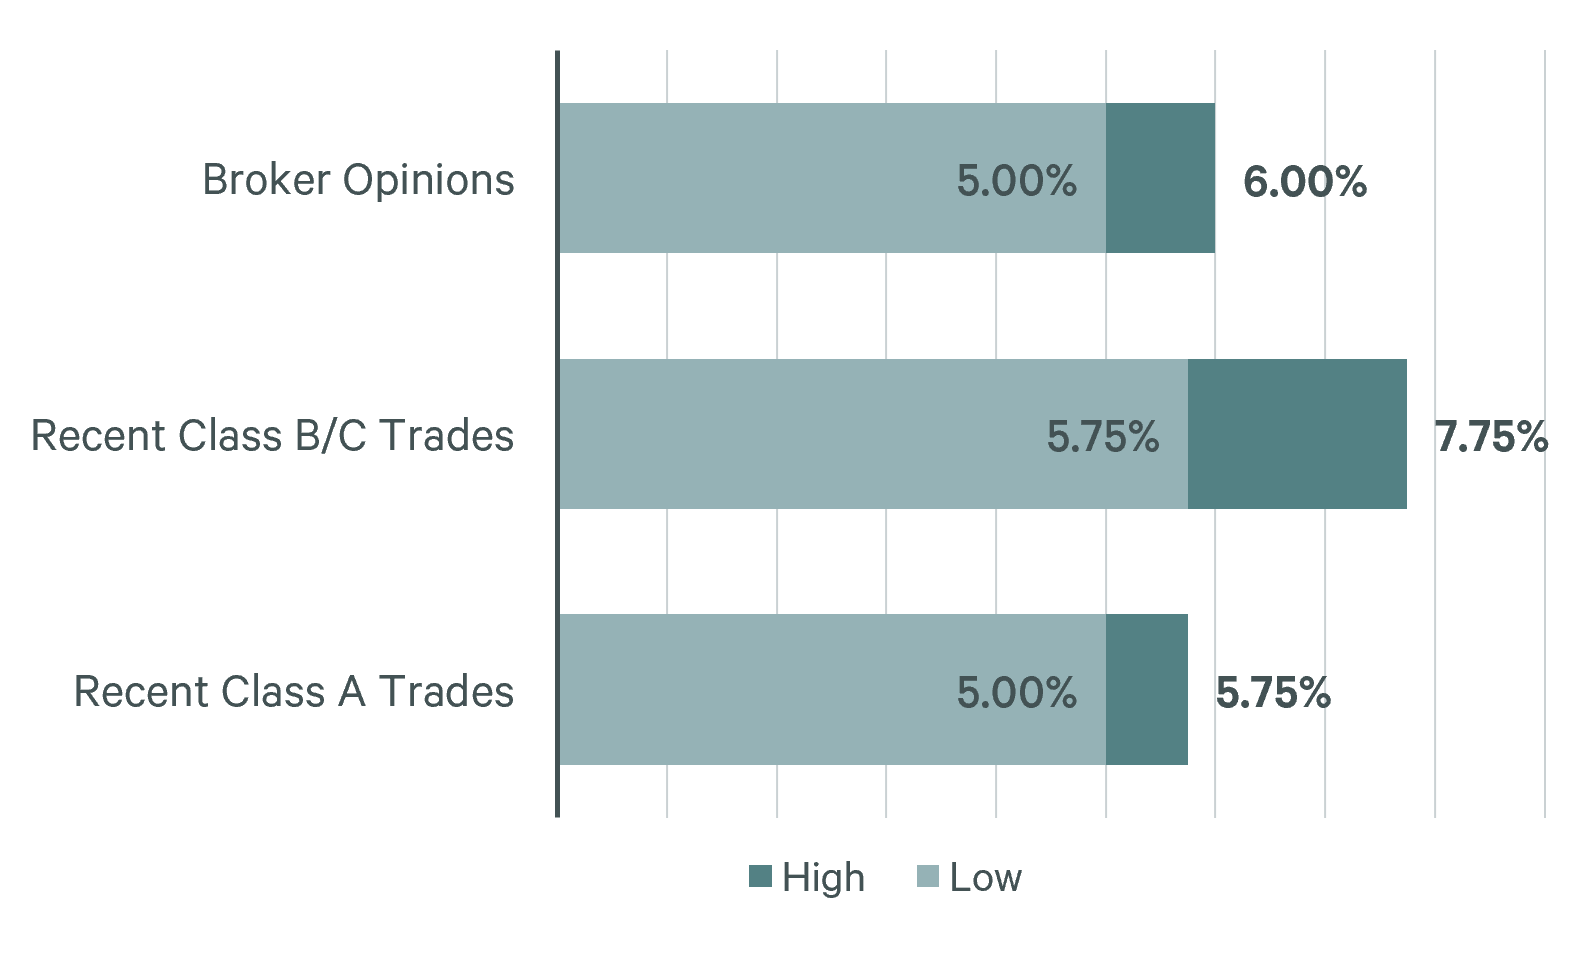
Recent sales of self-storage properties within the Southeast region show capitalization rates typically ranging from 5.00% to 5.75% for institutional Class A assets based on stabilized income, which generally coincide with broker market opinions. Class B trades are averaging 5.75% to 7.75%, with the upper end of the range in overbuilt market areas. Broker opinions generally run slightly more aggressive in the 5.00% to 6.00% range. Lower capitalization rates are primarily seen in the core market areas of South Florida/Miami, where there are significant barriers to entry, with somewhat higher capitalization rates seen in the denser areas of secondary markets such as Orlando and Tampa. Over the last 12 months, capitalization rates have been showing a downward trend, with increased investment in growing, secondary market areas due to population and rent growth upside, which is also evidenced by significant new construction occurring in these markets where there are lower barriers to entry.
Midwest Self-Storage Capitalization Rate Ranges
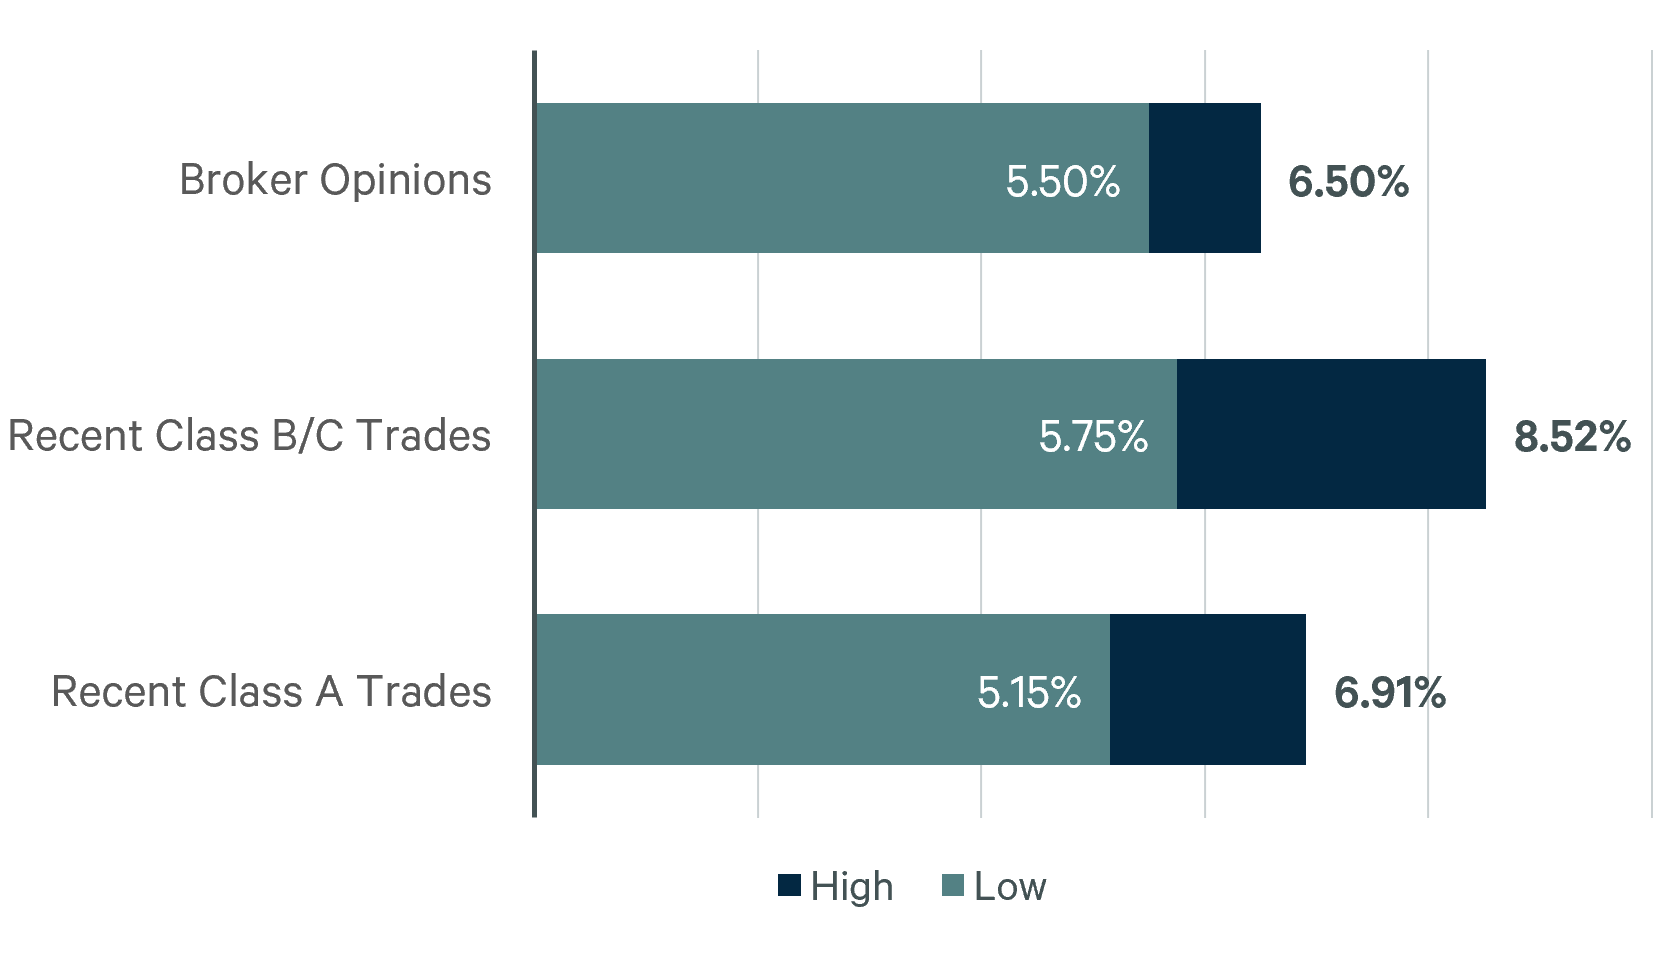
Recent trades of Midwest self-storage properties that closed over the past 12 months show capitalization rates for Class A assets ranging from 5.15% to 6.91%, Class B assets 5.75% to 8.52%, while broker opinions range from 5.50% to 7.00%, indicating reasonable consensus between market experts and real property data on current asset valuations. Transaction volume across the region has held steady, with activity spread across secondary and tertiary submarkets.
Notable recent sales include Extra Space Self Storage in West Bend, Wisconsin, September 2026 - $12.25m, Clover Self Storage Livonia, Michigan, August 2026 - $17.30m and Extra Space Self Storage in Joliet, Illinois, April 2026 - $23.00m.
MidSouth Self-Storage Capitalization Rate Ranges
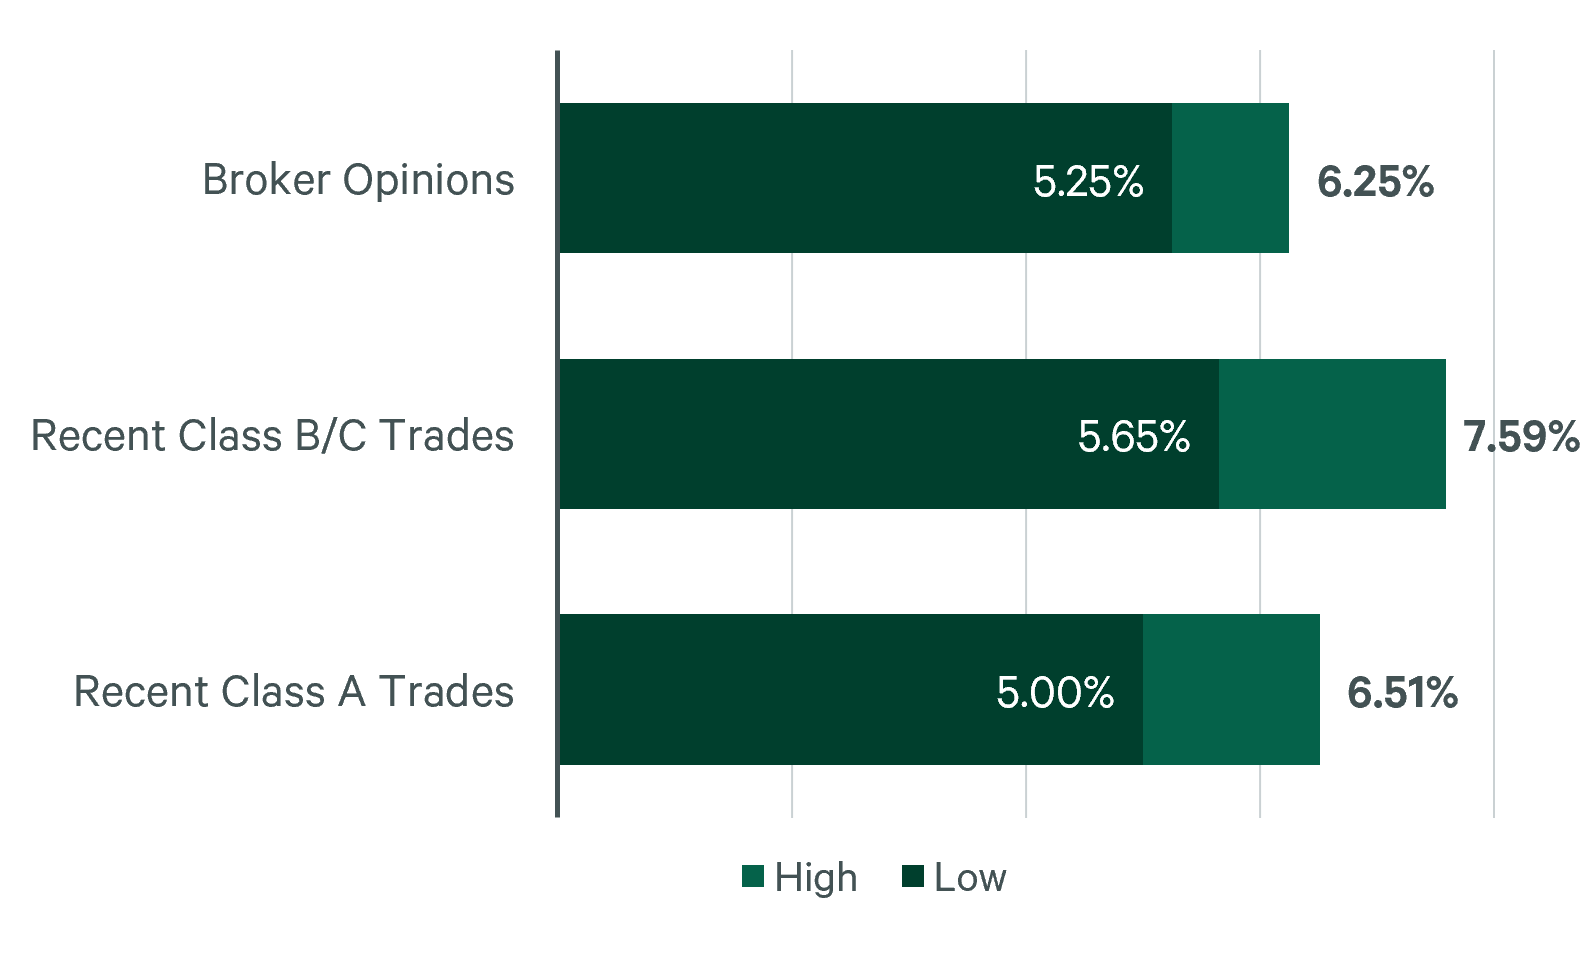
Since the beginning of the year, transaction data for Mid-South region self-storage properties indicates that actual capitalization rates are ranging between 5.00% and 6.51% for Class A and 5.65% to 7.59% for Class B, while broker market opinions lean toward a slightly narrower band of 5.25% to 6.25%. This difference suggests a general alignment between market analysts and transactional realities regarding baseline property valuations.
Notable examples of recent deal flow across the region include the sale of Storelocal Storage in Benson, Arizona, featuring 200 units along with vehicle parking; a prominent facility transaction in Crandall, Texas, arranged by Argus Self Storage Advisors; and several targeted asset acquisitions throughout the Tulsa MSA.
Mountain Self-Storage Capitalization Rate Ranges
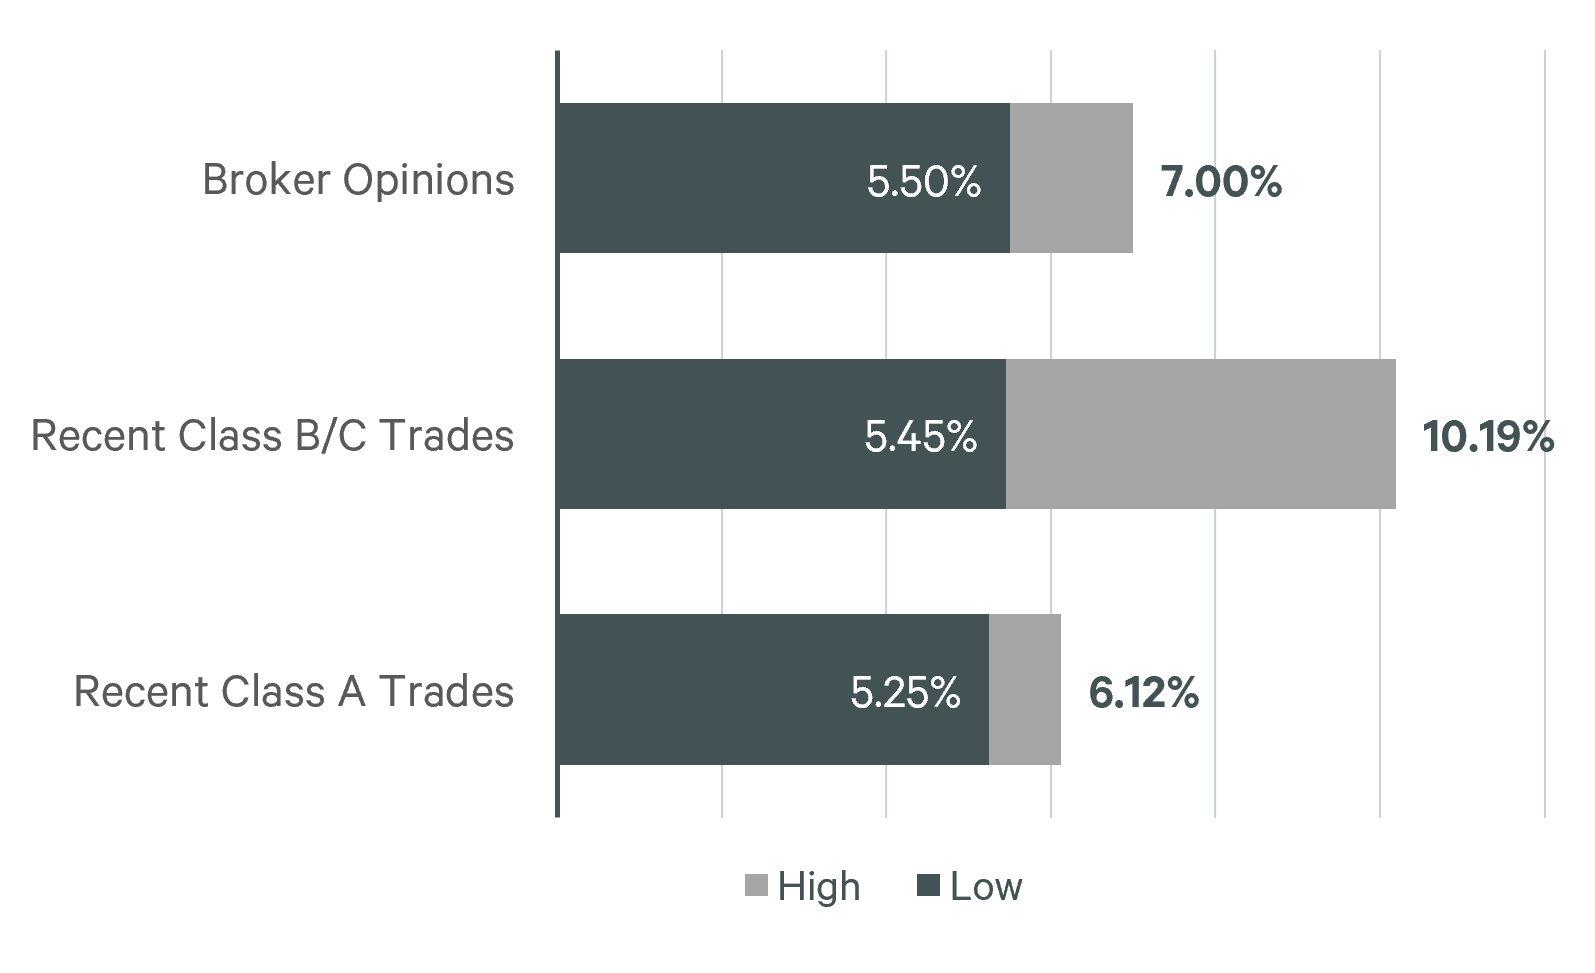
Recent sales of Mountain region self-storage properties that closed over the past 12 months show capitalization rates for Class A assets ranging from 5.25% to 6.12%, Class B assets 5.45% to 10.19%, while broker opinions generally range from 5.50% to 7.00%. Transaction volume across the region has held steady, with activity spread across secondary and tertiary submarkets.
Notable recent sales include Express Storage in Hayden, Idaho, May 2026 - $10.70m and Bayfield Self Storage in Bayfield, Colorado, June 2026 - $6.40m.
Pacific Self-Storage Capitalization Rate Ranges
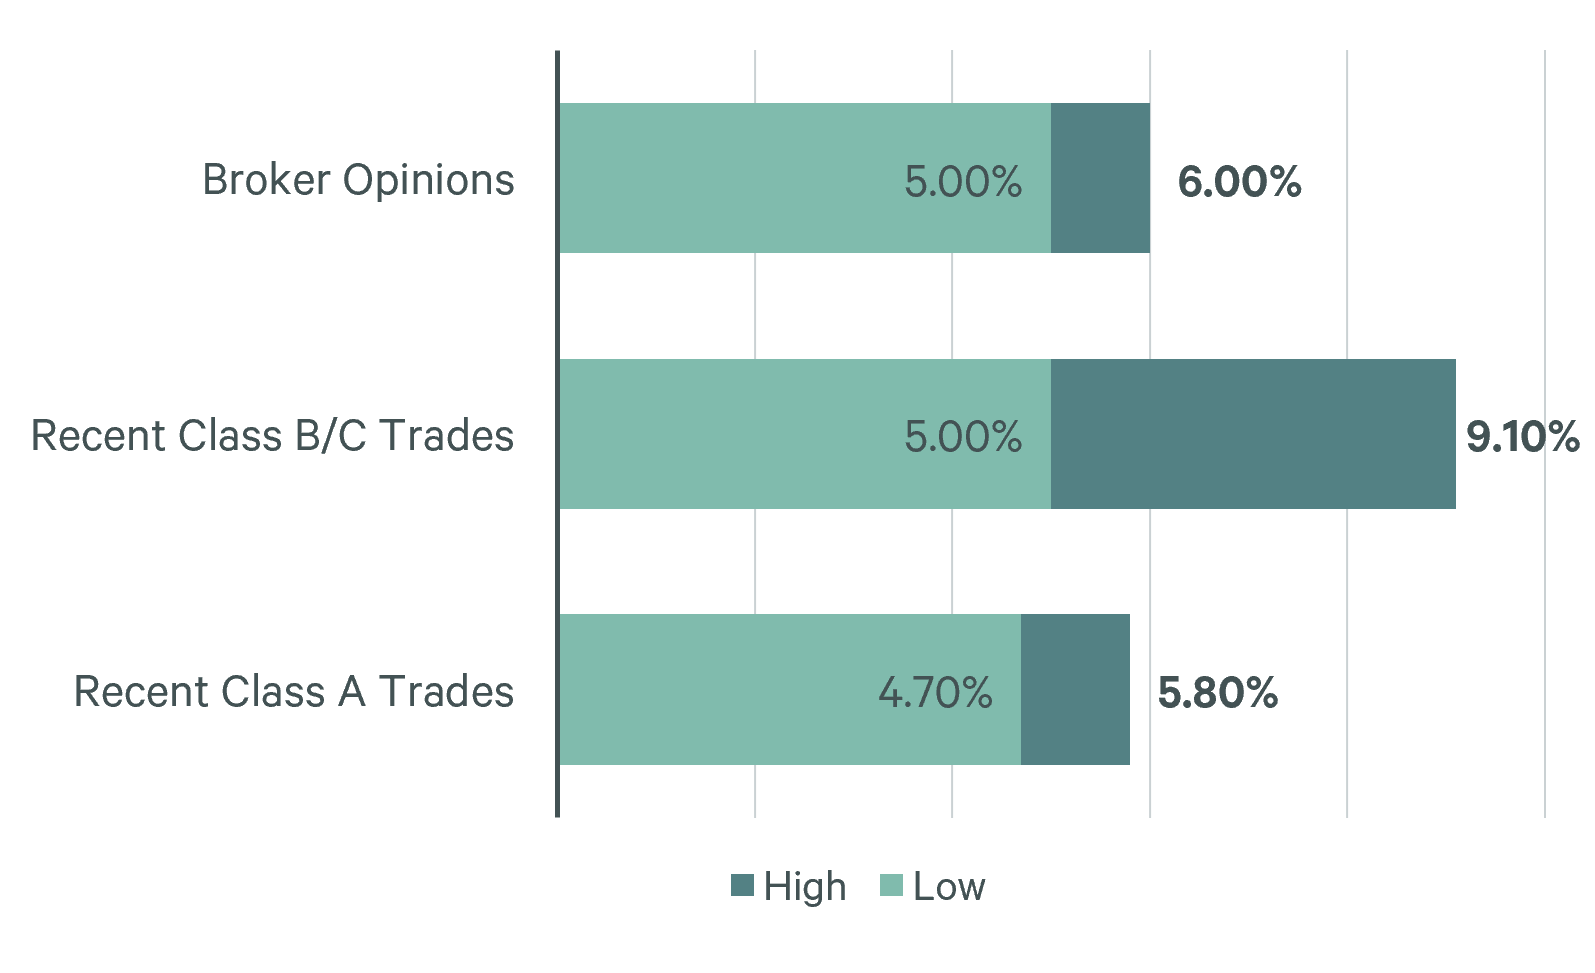
Recent sales of Pacific region self-storage properties that closed over the past 12 months show capitalization rates for Class A assets ranging from 4.70% to 5.80%, Class B assets 5.00% to 9.10%, while broker opinions generally range from 5.00% to 6.00%. Transaction volume across the region has held steady, with activity spread across secondary and tertiary submarkets.
Notable recent sales include Extra Space Self Storage in Fremont, California, October 2026 - $18.75m, Extra Space Self Storage in Phoenix, Arizona, July 2026 - $30.90m and Extra Space Self Storage in Happy Valley, Oregon, November 2026 - $18.50m.
Valuation & Advisory Services Contacts
Erik J. Lekberg, MAI
National Self-Storage Practice Leader

Chris Knobbe, MAI
VAS First Vice President
